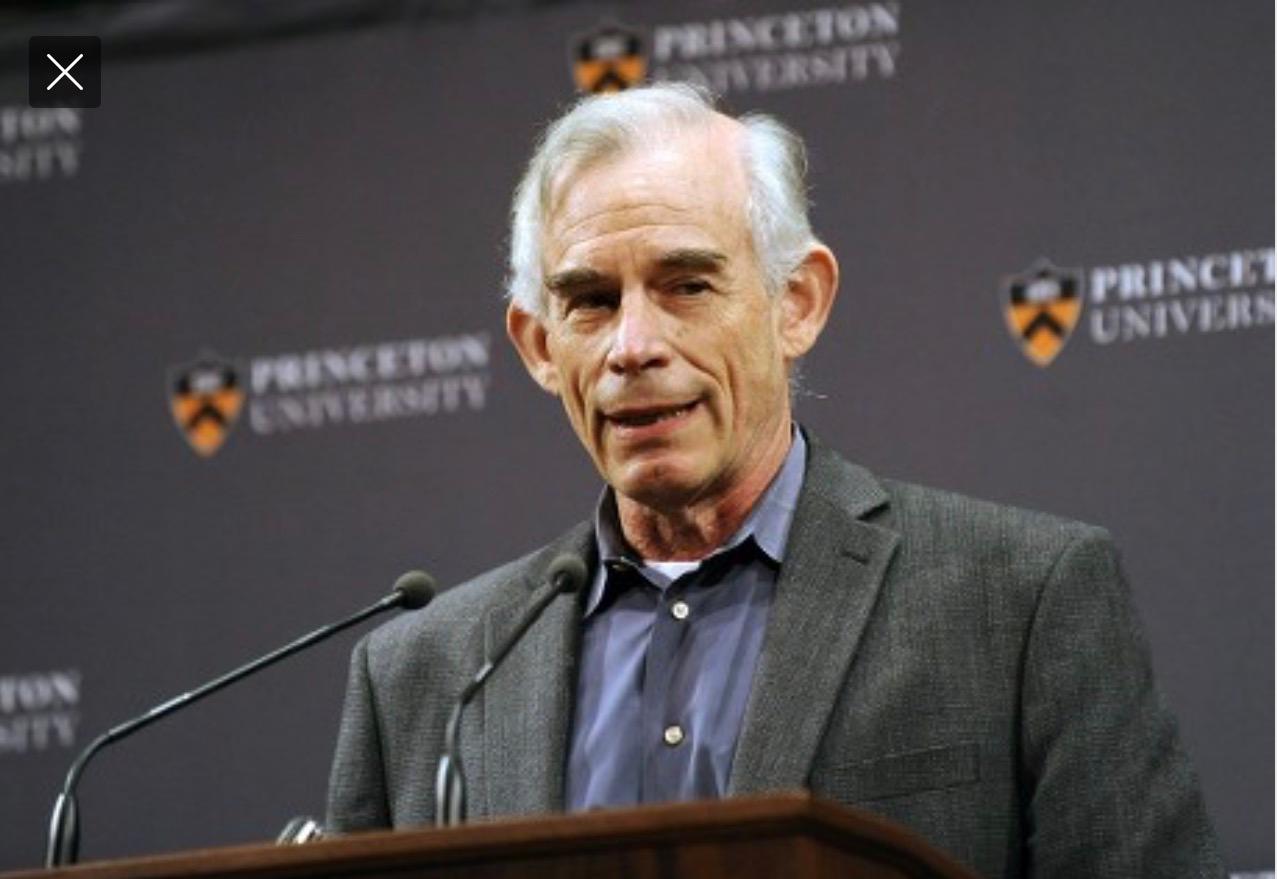
Christopher Albert Sims (October 21, 1942 – March 14, 2026), whose work stands as one of the most influential contributions to modern macroeconomics, passed away on March 14, 2026, leaving behind a legacy that fundamentally reshaped empirical macroeconomic analysis. Over the course of his distinguished academic career, Sims fundamentally reshaped empirical macroeconomic analysis by introducing the Vector Autoregression (VAR) framework, a methodological breakthrough that allowed economists to analyze the dynamic interactions among macroeconomic variables without imposing overly rigid theoretical assumptions. His research transformed both academic macroeconomics and the practical conduct of monetary policy, equipping central banks with powerful tools to identify economic shocks, understand transmission mechanisms, and evaluate policy interventions. In recognition of these groundbreaking contributions to the empirical analysis of cause and effect in the macroeconomy, Sims was awarded the Nobel Prize in Economic Sciences in 2011, jointly with Thomas Sargent.
VAR
Vector Autoregression (VAR) models represent one of the most important methodological innovations in macroeconomics. Introduced by Sims in his influential 1980 paper “Macroeconomics and Reality,” published in Econometrica, the VAR approach challenged the prevailing reliance on large, highly structured macroeconometric models that imposed strong theoretical assumptions about economic relationships. Sims argued that many of these restrictions lacked solid empirical foundations and could lead to misleading policy conclusions — famously characterizing such identifying assumptions as “incredible.”
Importantly, Sims did not reject large-scale macromodels outright. He acknowledged that they remained useful tools for forecasting and policy analysis, but argued that their structural interpretations were often unjustified. Instead, he proposed a more data-driven approach in which macroeconomic variables are treated as jointly determined within a dynamic system. This innovation fundamentally changed how economists model economic dynamics and analyze policy impacts.
In a VAR framework, each variable in the system depends on its own past values and the past values of other variables. A
Unlike earlier structural models that imposed predetermined causal structures, VAR models allow the empirical data to reveal the relationships among variables.
The VAR Breakthrough
Prior to the development of VAR, macroeconomic policy analysis relied heavily on large structural models that attempted to specify the entire economic system based on theoretical assumptions about consumer behavior, investment dynamics, and policy transmission. These models often contained numerous restrictions that were difficult to justify empirically.
Sims’ VAR framework introduced a major shift by emphasizing:
- Minimal theoretical restrictions, allowing data to determine dynamic relationships.
- Empirical identification of shocks, enabling economists to study how unexpected disturbances propagate through the economy.
- Transparent policy analysis, making it possible to assess the impact of policy interventions more objectively.
This approach significantly improved the credibility of empirical macroeconomic research and policy evaluation.
Key Analytical Tools Derived from VAR
VAR methodology gave rise to several analytical tools that are now standard in monetary policy analysis.
Impulse Response Functions (IRFs) These trace the effect of a shock in one variable — such as an unexpected increase in policy interest rates — on other macroeconomic variables over time.
Forecast Error Variance Decomposition This technique helps determine the proportion of fluctuations in a variable that can be attributed to different types of shocks.
Structural VAR (SVAR) Later developments incorporated identification restrictions to isolate specific economic shocks, including monetary policy shocks, demand shocks, and productivity shocks. The SVAR framework has become the standard tool for estimating dynamic causal effects in macroeconomics.
Influence on Monetary Policymaking
VAR models have had a profound impact on the practice of central banking. Institutions such as the Federal Reserve, European Central Bank, Reserve Bank of India and Bank for International Settlements routinely use VAR-based frameworks in their analytical and forecasting work.
The methodology has enabled policymakers to:
- empirically measure the transmission of monetary policy
- assess the macroeconomic effects of interest rate changes
- improve forecasting of inflation and output
- analyze macroeconomic shocks and policy trade-offs
Over time, VAR models have evolved into more sophisticated forms, including Bayesian VARs and factor-augmented VARs, which are widely used in modern macroeconomic forecasting and financial stability analysis.
Christopher Sims’ intellectual legacy extends well beyond the introduction of VAR. His contributions span econometric methodology, monetary theory, and the theory of decision-making under imperfect information. Beyond his research, Sims served as president of two of the leading professional organizations in economics: the Econometric Society in 1995 and the American Economic Association, reflecting the breadth of his influence across both econometrics and macroeconomics.
Vector Autoregression represents a major methodological shift in macroeconomics and monetary policy analysis. By allowing the data to reveal the dynamic interactions among macroeconomic variables, VAR models replaced rigid structural frameworks with flexible empirical systems capable of identifying economic shocks and tracing their effects through the economy.
Christopher Sims’ innovation therefore did far more than introduce a new econometric technique — it fundamentally reshaped the art and science of monetary policymaking, providing central banks with a powerful empirical lens through which to understand economic fluctuations and evaluate policy decisions.



Leave a Reply